
Of a lot lenders will get let you pay back the loan very early
Thirty years looks like lengthy. If you purchase a home while you are thirty five-years-old and possess a 30-year financial, their history percentage might be planned to possess right around committed you are able to old-age at the years 65.
Things really worth understanding regarding a thirty-seasons mortgage would be the fact because you might just take 3 decades to spend it off does not mean you are compelled to create therefore. Some create fees a pre-fee otherwise early payment punishment, but not. Before you can shell out even more on your mortgage, double-look at to verify that www.paydayloancolorado.net/federal-heights lender would not penalize you to have doing so.
If you’re finding repaying your mortgage very early, discover several a means to get it done. Should you get paid down biweekly, you can consider making biweekly repayments on your mortgage unlike month-to-month. Divide your monthly payment by 50 percent and pay one half whenever you have made the first income of the few days and the 2nd if you get paid off next time. Since there are 26 biweekly spend episodes within the a-year, you will end up investing thirteen months’ property value your home loan alternatively than a dozen.
An alternative choice is to try to increase an extra amount once you plan the payment. Also using a supplementary $one hundred otherwise $200 four weeks continuously can also be shave many years out-of your own mortgage.
How a 30-Seasons Repaired-Rate Financial Works
After you use and are generally approved for a thirty-season repaired-speed home loan, a couple of things are specific. Their interest doesn’t transform and your home loan was split to the some payments over the course of 30 years. New repayments become notice and you will principal together and remain a comparable from the mortgage.
Of many home owners as well as spend their property taxation and you may homeowners insurance advanced using their mortgage repayments. If you lay out less than 20% of price of your house, there are also to spend private mortgage insurance coverage (PMI) advanced up to you have paid down an adequate amount of the main so you’re able to equivalent 20% of home’s really worth.
Dominant and you will Notice
The loan principal is the matter you borrowed to cover your residence. If you purchase a $250,one hundred thousand home, spend a good 20% down payment of $50,000 and you will obtain $2 hundred,000, the new $2 hundred,100000 ‘s the loan’s principal. Since you create money on the home loan, the principal shrinks.
Notice is the payment billed by your financial to own giving you the borrowed funds. One method to look at it is the cost of doing team having a particular lender. Just as you could potentially spend an attorney otherwise a health care professional an effective payment for their characteristics, you have to pay the financial for their attributes when it comes to focus.
The price of bringing that loan can differ considerably off people so you can person because of attention. One borrower are available a beneficial 5% speed on a good $2 hundred,100 financing, if you’re some other debtor can be obtained a great step 3% rates.
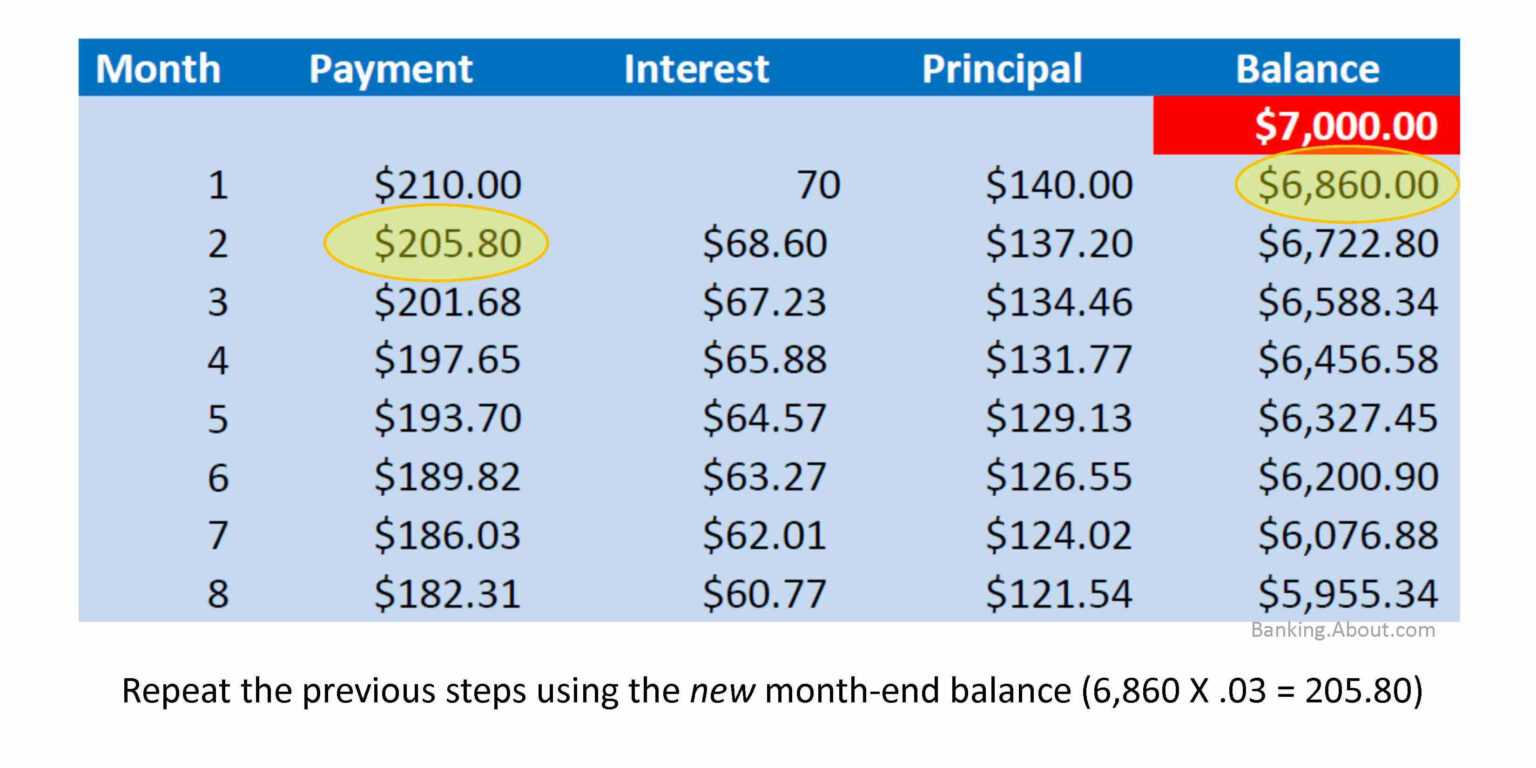
Just like the appeal try a share of the amount borrowed, it is large early in their payment period than it is at the end. Such as for example, when you initially begin making money in your $2 hundred,100000 financial, you are expenses 5% desire into $200,one hundred thousand. Since you processor chip out at dominating, it shrinks and so really does the attention in proportion.
Whilst you start out paying far more appeal than just principal in your financial and in the end start investing more toward the principal much less when you look at the attract, the commission you are required to build each month continues to be the exact same due to some thing called amortization.
Amortization Schedule
Financing amortization involves paying down the debt more the precise several months which have fixed money. Whenever a mortgage was amortized, the principal and you can appeal are combined. They differs from other sorts of mortgage payment schedules since you afford the same amount and you will know very well what you pay on a monthly basis. Including mortgages, other sorts of repayment loans, such as auto loans and you will student loans, usually rating amortized.